voices quoted
How a Tier-2 SaaS crossed ₹170 crore
How a bootstrapped SaaS knowledge-base platform crossed ₹170 crore from Tier-2 India — and why documentation tools are the quiet winners of the AI era.

The short version
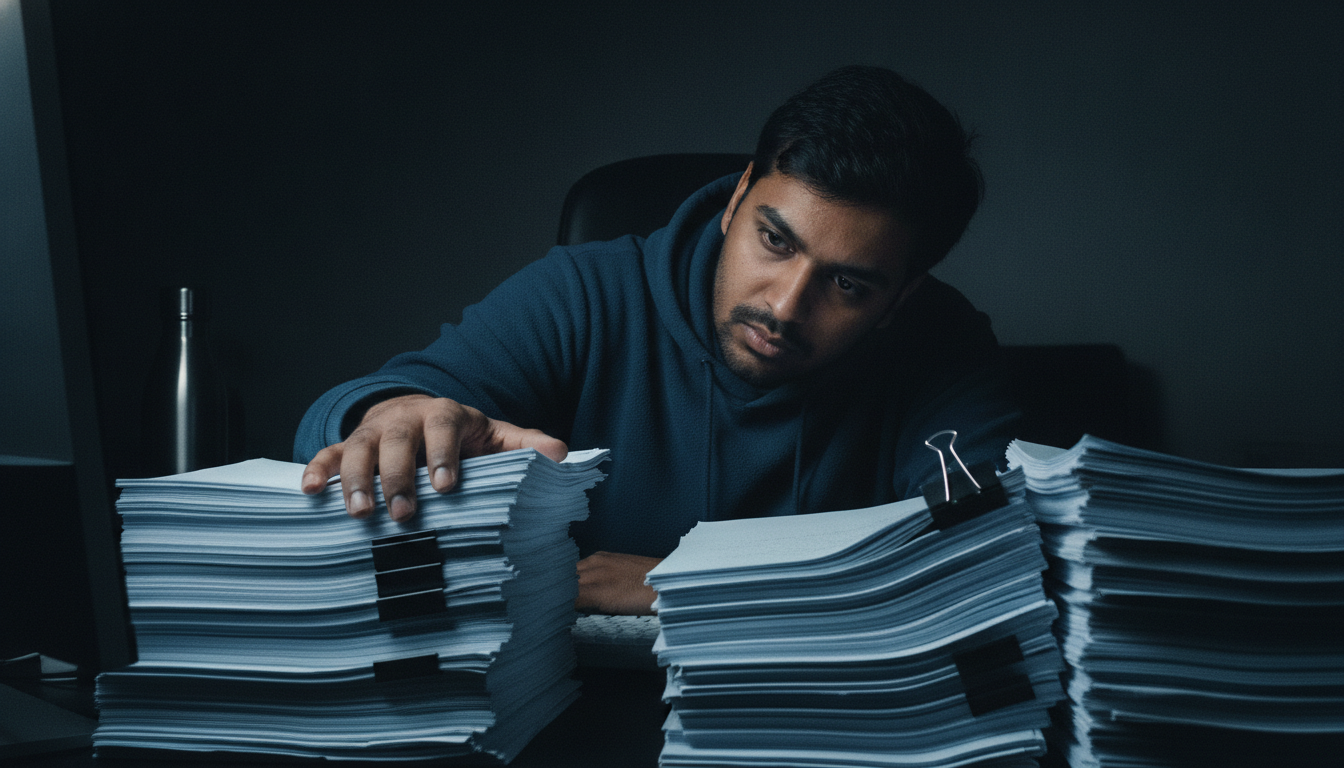
Kovai.co's Document360 crossed ₹85 crore ARR with zero VC money, 250 people in Coimbatore, and 30-40% year-on-year growth. The playbook: pick a category AI is making more valuable (not less), stay lean in a Tier-2 city, and reinvest product revenue into R&D instead of fundraising rounds.
Key highlights
- 1 Documentation tools are a ₹40,000 crore global market — and growing fast
- 2 Document360 hit ₹85 crore ARR with no VC funding
- 3 Coimbatore keeps burn low enough to compound without dilution
- 4 AI is making documentation more valuable, not obsolete
- 5 30-40% compounding growth from ₹85 crore, with zero VC
- 6 Credits-based pricing is replacing per-seat SaaS models
Kovai.co just crossed ₹85 crore ARR with Document360 — its AI-powered knowledge base platform — making it one of the rare bootstrapped Indian SaaS companies to run two products past that mark simultaneously. The other is BizTalk360. Combined revenue now exceeds ₹170 crore. And the next target — $25 million ARR by 2028 — is backed by a ₹220 crore investment into their Coimbatore development centre.
The Market is ₹40,000 Crore — and AI is Accelerating It
The global software documentation tools market was valued at roughly ₹40,000 crore ($4.71 billion) in 2025, growing at 7.8% annually, according to WiseGuyReports. A narrower slice — AI-native developer documentation assistants — is growing at 21.7% CAGR and is projected to reach ₹1,39,400 crore ($16.4 billion) by 2034, per Dataintelo. That is not a niche anymore.
North America commands 38% of enterprise demand. Asia-Pacific sits at roughly 20-24% and is climbing. The competitive field is crowded: Docusaurus holds 34% market share as a new entrant, GitBook trails at 7.7%, and incumbents like Atlassian (Confluence), Microsoft, Adobe, and MadCap Software hold the enterprise middle. Atlassian added AI-assisted authoring to Confluence in June 2024. Readme partnered with IBM in February 2025 to deepen API documentation integration.
Document360 is not competing on market share statistics yet. It is competing on a specific gap: self-service knowledge bases for SaaS and enterprise companies who need something between a basic wiki and a full-blown Confluence deployment. That gap is real, and 1,500 paying customers — including VMware, NHS, Ticketmaster, Payoneer, Virgin Red, and Comcast — confirm it.
Shahed Nasser, Head of DX at Medusa, put the AI dynamic plainly:
Good documentation doesn't just support your product — it is your product. AI is making good documentation more important, not less, because without technical documentation, AI assistants wouldn't be able to provide actual answers.
Every SaaS product that adds an AI assistant now needs structured, maintained documentation underneath it. That is the tailwind Document360 is riding.
The No-VC Playbook: How You Reach ₹85 Crore Without a Funding Round
Most SaaS founders treat fundraising as the default growth lever. Kovai.co never did. Saravana Kumar built BizTalk360 first — a monitoring tool for Microsoft BizTalk Server environments — and let it mature into a cash-generating product. That product now funds Document360's R&D at close to ₹85 crore per year in combined product investment.
This is the bootstrapped flywheel: Product A reaches maturity → throws off cash → funds Product B's growth phase → repeat. It is the same model that Konnect Insights used to approach ₹85 crore ARR without VC and that Recruiterflow used to cross ₹50 crore ARR in HR SaaS — internal capital compounding instead of dilution.
Kumar has been explicit about the ambition: "Eventually, we want to build a $100 million business." At 30-40% annual growth for Document360, and an estimated 40-45% growth projected for 2026, the math is not fantasy. ₹850 crore in total ARR by the end of the decade is the stated destination.
The comparison to VC-backed peers matters here. A funded competitor raising ₹200 crore at Series B is buying growth — hiring aggressively, subsidising customer acquisition, burning toward a metric. Kovai.co is growing at similar rates while keeping every rupee of equity. The trade-off is speed; the advantage is permanence.
Coimbatore as a Structural Cost Advantage
The ₹220 crore investment into Coimbatore over three years is not philanthropy. It is a deliberate unit-economics decision. A 250-person engineering team in Coimbatore costs a fraction of what the same team costs in Bengaluru or Hyderabad — let alone London or San Francisco. That gap in burn rate is what lets Kovai.co reinvest aggressively into product without needing external capital.
Coimbatore has a growing SaaS ecosystem. It is not Bengaluru, which means talent is less competed-for and attrition is lower. For a bootstrapped company, that stability compounds: engineers who stay for three years build institutional knowledge that a funded startup, cycling through VC-pressured hiring and firing, cannot replicate.
The London office handles sales and founder proximity to global enterprise clients. The Coimbatore centre handles everything that actually builds the product. That split — global face, Tier-2 engine — is a model more Indian SaaS founders should study. The ₹220 crore commitment signals that Kovai.co is not treating Coimbatore as a cost centre to eventually outgrow. It is the core.
Delfina Hoxha, Founder of Little Language Models, frames the documentation-as-sales-engine argument that makes this investment make sense:
When the information architecture is right, customers can self-serve the sales process. They find what they need, they understand the product, they make the decision — without needing a call.
For a company selling documentation software, this is recursive: their own product philosophy — good docs reduce support and sales costs — applies to their own business model. A Coimbatore team building better documentation tooling is, in effect, reducing Kovai.co's own CAC (customer acquisition cost — how much it costs to win one new paying customer).
AI as a Tailwind, Not a Threat
The conventional anxiety for SaaS founders in 2025 is that AI will commoditise their category. For documentation tools, the opposite is happening. Every company deploying an AI chatbot, an AI support agent, or an AI onboarding assistant needs a structured knowledge base underneath it. Without that base, the AI hallucinates. With it, the AI becomes genuinely useful.
Document360's customers are not just storing docs anymore. They are feeding those docs into AI layers that power customer support, onboarding, and self-service sales. The knowledge base becomes the training data. That shifts the product from a nice-to-have to infrastructure.
Mirna Wong, a documentation professional at dbt Labs, points to the human judgment that AI cannot replace in this workflow:
You need to know your users. AI doesn't know your users. Documentation strategy must be grounded in understanding who is actually using the docs and what they need.
This is why Document360's 1,500-customer base — spanning IT, SaaS, manufacturing, healthcare, and government — matters. Each vertical has different user needs, different doc structures, different compliance requirements. A platform that has built for that diversity has a moat that a generic AI writing tool cannot easily cross.
Kumar acknowledged the disruption directly, noting that AI creates "winners and losers" in SaaS — and that documentation is in the winners' column. The category is also seeing a pricing model shift as a result.

Credits-based Pricing: What the Model Shift Means for SaaS Founders
For years, SaaS pricing was simple: pay per seat (per user per month). A company with 50 employees pays for 50 seats. That model is cracking under AI adoption.
Kovai.co has already moved some customers to credits-based pricing. Instead of paying for access, customers pay for usage — each AI-generated summary, each automated doc update, each knowledge-base query consumes credits. This is how AWS prices compute, how OpenAI prices API calls, and increasingly how AI-native SaaS companies price everything.
The business logic: AI features have variable compute costs. A user who runs 10,000 AI queries a month costs more to serve than one who runs 100. Per-seat pricing hides that variance. Credits-based pricing exposes it — and lets the vendor capture value proportional to usage, not headcount.
For Document360's enterprise customers, this is not friction. It is alignment. They pay more when they use more, less when they use less. For Kovai.co, it is a revenue expansion mechanism: as customers embed Document360 deeper into their AI workflows, their credit consumption — and their bill — grows without a new sales motion.
This is the same structural shift playing out across the SaaS industry. Founders still running pure per-seat models in AI-adjacent categories should watch this closely. The ₹60 crore revenue, 50% margin playbook that bootstrapped services-as-software companies have built depends on pricing models that scale with value delivered — credits-based is the next version of that.
30-40% Growth, Consistently: What the Compounding Actually Looks Like
Document360 launched in 2019. It crossed ₹85 crore ARR in late 2025 — six years of building. At 30-40% annual growth, that trajectory is not explosive by VC standards. It is, however, extremely durable.
At 40% growth from ₹85 crore ARR:
- Year 1 (2026): ~₹119 crore
- Year 2 (2027): ~₹167 crore
- Year 3 (2028): ~₹212 crore
The stated target is ₹212 crore ($25 million) by 2028. The math checks out — if the growth rate holds. Kumar's projection of 40-45% growth for 2026 suggests confidence that the AI tailwind is already showing up in pipeline.
The enterprise client list is the proof point. VMware, NHS, Ticketmaster, Comcast — these are not SMB trial accounts. They are sticky, high-ACV (annual contract value — the total revenue from one enterprise customer per year) relationships that churn slowly and expand over time. An NHS contract that starts with one department frequently spreads to three. That is the enterprise expansion motion that makes 30-40% growth sustainable without proportional increases in sales headcount.
Sarah O'Keefe, an independent documentation consultant, has observed that structured content is what AI systems consume most effectively — documentation that is consistent and well-organised is more useful to AI than unstructured prose. Document360's architecture, built for structured knowledge bases from day one, positions it well for the AI-consumption era.
Conclusion
Kovai.co's Document360 milestone is not a feel-good Tier-2 story. It is a repeatable SaaS model: pick a category AI is making more valuable, stay lean where talent is stable, let one mature product fund the next, and grow at 30-40% without dilution. The ₹220 crore Coimbatore bet is the next compounding cycle. Watch whether Turbo360 becomes the third ₹85 crore ARR product — that is when the model becomes undeniable.
5 Questions Founders Actually Ask
Can a SaaS company actually win enterprise clients from a Tier-2 city?
Why is AI making documentation tools more valuable, not less?
What is credits-based pricing and how is it different from per-seat SaaS?
How does a bootstrapped company compete against funded rivals in enterprise SaaS?
Is a ₹220 crore investment in a Tier-2 development centre a real competitive moat?
Find the exact growth leak in your business — in 2 minutes.
Paste your URL. Our AI agent crawls your site, diagnoses what's broken, and ships a step-by-step fix plan. Free, no signup.
Run free audit